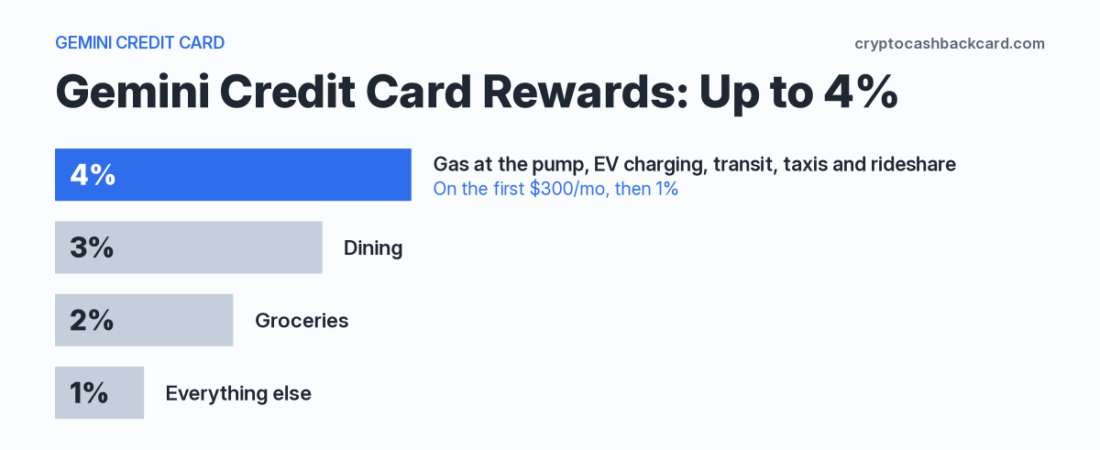
Short answer: the Gemini Credit Card is a no-annual-fee Mastercard that pays crypto instead of cash back. It earns up to 4% on gas at the pump, EV charging, transit, taxis and rideshare (on the first $300 a month, then 1%), 3% on dining, 2% on groceries and 1% on everything else. It is worth it if you live in the U.S., pay your statement in full every month and want your rewards in crypto. Skip it if you carry a balance (purchase APR is 18.74%–34.74%), want a sign-up bonus (paused since January 31, 2026) or expect quick customer service. Below: the terms, the real credit limits cardholders report, the merchant-code surprises, the tax angle and what Reddit says.
CryptoCashbackCard is an independent site and is not affiliated with or endorsed by Gemini or WebBank. This page has no affiliate links. It is general information, not financial or tax advice. Terms checked October 31, 2026; card terms change, so confirm them in the Gemini app before you apply.
Gemini Credit Card at a glance
| Item | What the terms say |
|---|---|
| Issuer / network | WebBank (Utah); Gemini Constellation, LLC services the account; Mastercard World Elite |
| Annual fee / foreign transaction fee | $0 / none |
| Rewards | 4% gas at the pump, EV charging, transit, taxis, rideshare (first $300 a month, then 1%); 3% dining; 2% groceries; 1% everything else |
| Paid in | Bitcoin by default, or 50+ coins you can switch at any time |
| Purchase APR | 18.74%–34.74% variable per the Rates & Fees sheet (the cardholder agreement of the same date says 16.74%–34.74%; see below). No intro APR found |
| Late payment fee | Up to $25 the first time; up to $35 if you were charged a late fee in the prior six billing cycles |
| Cash advance | $10 or 3%, whichever is greater; 29.74% APR from day one |
| Welcome bonus | Paused for cards approved after January 31, 2026 |
| Credit check | Soft-pull pre-qualification, then a hard inquiry if you continue |
| Availability | U.S. residents only; you must stay a U.S. resident while the account is open |
Our verdict: who it is for and who should skip it
It fits you if you:
- pay the full statement balance every month, so purchases never cost interest;
- spend on dining (3%) and at supermarkets (2%), plus some gas, EV charging, transit or rideshare (4% on the first $300);
- want to build a crypto position from spending you already do, and can live with the price going up or down;
- live in the U.S. and do not need the card at Costco.
Skip it if you:
- carry a balance. At 18.74%–34.74% APR, interest can wipe out the rewards (math below);
- want a sign-up bonus. The $200 offer is paused;
- spend mostly at Costco, Sam’s Club, Walmart or Target, or on delivery apps. These often earn only 1%;
- expect fast, easy customer service. Complaints about support and frozen accounts are the card’s weakest point (see below);
- want a card for business spending. The personal card’s terms bar business use.
What the big reviews miss
Most Gemini card reviews restate Gemini’s rate table. We looked for what a rate table cannot tell you:
- Real credit limits. We gathered 33 starting limits cardholders reported. The median is $2,000.
- Merchant-code surprises. Your rate depends on how the merchant is coded, not on what you bought. Paying inside a gas station, Target, Walmart and delivery apps are the usual traps.
- The cap in dollars. The 4% tier tops out at $12 a month.
- Tax. The IRS has no ruling written for crypto card rewards, and what you do with the crypto later is a taxable event.
- What cardholders say. A dated summary of Reddit, plus the BBB record, with the limits of that evidence.
Gemini Credit Card rewards
| Rate | Category (per Gemini) | Limit |
|---|---|---|
| 4% | Gas at the pump, EV charging, transit, taxis, rideshare | $300 combined per calendar month, then 1%; resets on the 1st |
| 3% | Dining: “generally includes traditional restaurants, bars/nightclubs, and fast food” | No cap listed |
| 2% | Groceries: traditional grocery and specialty food stores (excludes Costco, Sam’s Club, Walmart, candy stores, bakeries) | No cap listed |
| 1% | All other qualifying purchases | No cap listed |
| Up to 10% | Rotating “Vault Rewards” merchant offers; the current brands are listed in the Card tab of the Gemini app | Limited time; monthly spend limits may apply |
The 4% cap, in dollars
Gas, EV charging, transit, taxis and rideshare share one $300 monthly bucket. At 4%, that is at most $12 a month, or $144 a year. The same $300 at the 1% base rate would earn $3, so the 4% tier adds about $9 a month. If you spend $400 in the category, you earn $12 on the first $300 and $1 on the last $100, so $13.
What a normal month might earn
This is our arithmetic on a made-up $2,000 month, not a typical user:
| Spend | Amount | Rate | Reward |
|---|---|---|---|
| Gas, transit, rideshare (under the cap) | $200 | 4% | $8.00 |
| Dining | $400 | 3% | $12.00 |
| Groceries at supermarkets | $500 | 2% | $10.00 |
| Everything else | $900 | 1% | $9.00 |
| Total | $2,000 | 1.95% blended | $39.00 |
If that $500 of groceries went to Costco, Sam’s Club, Walmart or Target, which Gemini says typically earn 1%, the total falls to $34, or 1.7%. A card that mostly earns 1% to 2% is not special on rate alone; the pitch is getting that value as crypto.
The merchant-code surprises
Gemini’s support page says merchant category codes (MCCs) are “assigned by the merchant’s payment processor, not Gemini” and a purchase “will earn only 1% back even if it appears to fall within a higher-tier category.” Gemini itself names these traps:
- Gas inside the station. Only paying at the pump earns 4%. Inside the store or at the kiosk is “not eligible.” Five cardholders we found said paying inside earned 1%; five said paying at the pump earned 4%.
- Costco, Sam’s Club, Walmart, Target. Often 1%, even for food. U.S. Costco warehouses and Costco gas stations accept Visa as their only credit card, so the Gemini Mastercard cannot be used there in person. A Gemini representative said in 2025 that Sam’s Club gas earns 4% at the pump.
- Uber Eats and delivery apps. Gemini says they “may not be coded as restaurants.” We found no current cardholder report either way.
- Parking and EV charging networks. No cardholder data found. Unknown.
Our full merchant-by-merchant table is in Gemini Credit Card Categories: Which Merchants Earn 4%?
How the crypto rewards arrive
Most rewards are “instant”: Gemini calculates them when the purchase is authorized and adjusts when it posts. Online merchants, hotels, gas stations and car rental companies pay only after the charge posts, normally 24 to 72 hours. Returns reduce your rewards: Gemini can recover rewards on a reversed purchase by adding a “Rewards Charge” to your card balance. Rewards land in a Gemini Exchange account, in bitcoin unless you pick another coin, and you can change the coin at any time for future purchases.
In our own account (rounded, rewards set to XRP for 13 months), we earned about 600 XRP on roughly $21,000 to $33,000 of spending. That was worth about $800 at the XRP price on October 22, 2026. That is a one-day snapshot, not what the rewards were worth when they were credited, and it is one account, not a sample. See the Gemini XRP Edition card for how the design relates to the reward coin.
Gemini’s terms say no rewards rate is guaranteed, the program can change, and it “may be terminated at any time for any reason without advance notice.” Gemini also reserves the right to add exclusions at any time.
Real Gemini credit limits: what 33 cardholders report
Gemini publishes no minimum or maximum credit limit. So we collected 33 starting limits that cardholders reported in public forums (r/Gemini, myFICO) and one BBB case, then counted one value per person.
- Median starting limit: $2,000. Range: $1,000 to $24,000. Average $5,379, pulled up by a few high limits.
- 17 of 33 (52%) reported $2,000 or less. 7 of 33 (21%) reported exactly $1,000. 6 of 33 (18%) reported $10,000 or more.
- The two highest ($19,500 and $24,000) come from early-era accounts (around 2021–2022). Recent approvals may run lower, but our sample is too small to prove it.
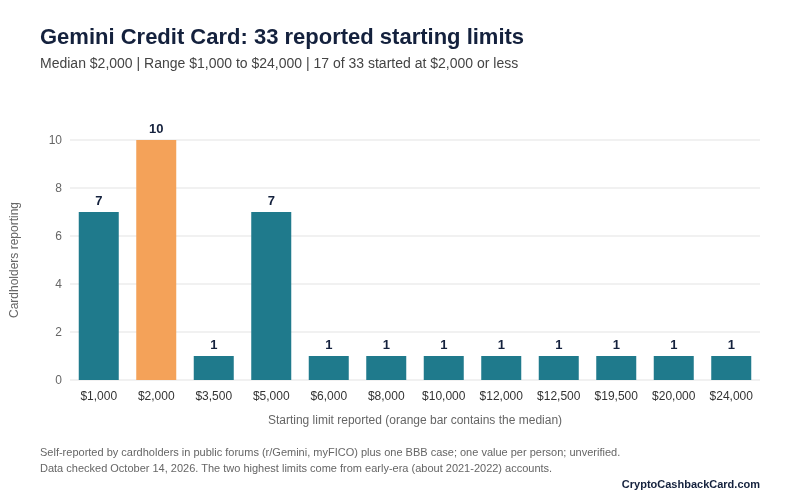
These numbers are self-reported and skew toward people who post about problems. Your limit depends on WebBank’s review of your application. The details, including how limit increases work, are in Gemini Credit Card Credit Limit: 33 Real Limits.
Limit fine print that matters
- Temporary lower limit. The agreement says that if you use the virtual card before you receive, activate and use the physical card, your available credit “may be less than your Credit Limit.” One BBB case shows a $5,000 limit with a $1,500 temporary limit until activation.
- Payments free up credit slowly. A payment made before the cycle ends may not restore your available credit until the later of the next cycle’s first day and when funds clear, which “may take up to seven (7) Business Days.”
- Increases. Gemini’s support page says you can request an increase “if your account is eligible,” through Card Settings, with a soft inquiry and no guarantee. The agreement says Gemini periodically reviews accounts using factors such as on-time payments and whether the account has been over the limit. Cardholders report an increase button after about three months. In our counts, 11 people reported denials and 7 reported approvals; that is not an approval rate, because people choose whether to post.
Fees and APR
| Fee or rate | Gemini Credit Card |
|---|---|
| Annual fee | None |
| Foreign transaction fee | None |
| Purchase APR (variable) | 18.74%–34.74% (Rates & Fees, Sept. 25, 2026). The Cardholder Agreement of the same date says 16.74%–34.74%. Maximum APR 35.99% |
| Cash advance APR / fee | 29.74% from the transaction date / $10 or 3%, whichever is greater |
| Penalty APR | 33.74% after late payments in two consecutive months, two months in any six, or a returned payment |
| Late payment fee | Up to $25; up to $35 if a late fee was charged in the prior six cycles |
| Returned payment fee | $25; $35 for a second within six cycles |
| Card replacement | One free per 12 months, then $50 |
| Intro APR | None found |
Paying in full matters. Your payment is due at least 25 days after the cycle closes, and purchases cost no interest if you pay the whole statement balance on time. If you pay less even once, you lose that grace period and regain it only after two full-payment cycles.
Why carrying a balance defeats the card
Our arithmetic (balance x APR x 30/365, simplified): carrying $1,000 for one 30-day cycle costs about $15.40 in interest at 18.74% and about $28.55 at 34.74%. The $2,000 example month above earned $39, or about $19.50 per $1,000 spent. One cycle of interest on a $1,000 balance can take back most of a month’s rewards on that same $1,000.
Gemini Credit Card benefits beyond the rate table
- Metal card for every approved cardholder. The card number is not printed on it; you view it in the app.
- Works with Apple Pay, Google Pay and Samsung Pay. Contactless works after you make one chip or swipe purchase with the physical card.
- Choose from seven designs (black, silver, rose gold, and BTC, XRP, SOL and ZEC editions). The designs do not change the benefits.
- Up to five authorized users (they do not earn rewards themselves; the primary cardholder does).
- Mastercard World Elite network benefits, subject to Mastercard’s terms.
- Referral program for cardholders. Gemini’s referral terms exclude marketing affiliates.
The honest cons
1. Customer support and frozen accounts
This is the card’s most-reported weakness, so we checked several places. The numbers and their limits:
- BBB (checked October 31, 2026): Gemini Credit Card is not BBB accredited and has a B rating. BBB lists 76 complaints in the last three years (42 in the last 12 months), 34 of them billing issues. BBB does not verify complaints, and the rating changes.
- Trustpilot: the Gemini company page shows 1.3 out of 5 from about 1,500 reviews. That page covers Gemini as a whole, including the exchange, not just the card, and some reviews are about customer service in general.
- Reddit: in four threads we read (see below), commenters who described their own card use were split about evenly: 7 positive and 6 negative. The negative ones were about slow support, declined transactions, hard-to-file disputes, and frozen or closed accounts. In a Gemini escalation thread on r/Gemini, where users post support ticket IDs for Gemini staff to escalate, at least three commenters tied an account problem to their credit card, including one whose card-linked account was stuck in verification for almost a year. That thread started in mid-2025, so it is more than a year old.
The agreement lets Gemini suspend or close the account “at any time, with or without cause,” and your card account must stay tied to a Gemini Exchange account in good standing. If your exchange account is frozen, your card access can be affected. For how exchange risk differs from card fraud, see are crypto credit cards safe?
2. Crypto price risk
Your reward is worth whatever the coin is worth. It can rise or fall after you receive it. Gemini advertises that bitcoin rewards earned from October 2021 to July 2024 and held through July 2025 gained an average of 277%. That is a favorable window that ended over a year ago, and Gemini adds that past performance is not indicative of future results. Do not treat it as a forecast. If you plan to sell rewards for dollars right away, check Gemini’s fee schedule for selling first; we did not verify those fees.
3. The headline 4% is small
The 4% tier is capped at $12 a month. The base rate is 1%. The blend in our example is about 2%.
4. No sign-up bonus and no intro APR
Gemini paused the $200 bonus ($3,000 spend in 90 days) for cards approved after January 31, 2026, per its promotional terms. We found no public replacement. There is no intro APR.
What Reddit says about the Gemini Credit Card
Searching for “gemini credit card reddit” turns up mixed threads. In the four we read (r/Gemini and r/CreditCards, mid-2025 to November 2025; 11 to 15 months old, so dated):
- Positive: rewards arrive without trouble (at least 4 commenters); it works anywhere Mastercard does except Costco; some use it only for the 4% and 3% categories and another card for everything else; two said their rewards had gained in value.
- Negative: support is slow or unhelpful; random declines and hard disputes (one detailed post, November 2025); frozen or closed accounts; the 4% cap is “only $12 a month”; a flat-cash card may earn more; tracking your reward cost basis for taxes is a chore.
- On limits: “low limit plus slow payment release” is a recurring complaint (6+ users in earlier threads).
This is not a poll. People post when something breaks, and these are old threads. Treat it as a list of what to check, not a score.
Are Gemini Credit Card rewards taxable?
The IRS has not published guidance written for crypto credit card rewards. Rewards earned by spending are commonly treated as a rebate (a discount on your purchases) rather than income, but that is an analogy to general IRS rules, not a crypto-specific ruling. Selling, trading or spending the crypto later is taxable, so you may owe tax on any gain, and you should keep records of the date and dollar value of each reward. Bonuses that do not require spending can be different: Gemini’s referral terms say referral rewards over $600 in a calendar year are reported on Form 1099-MISC. Gemini’s own rewards terms say you are responsible for your tax liability. Read our full guide, Are Crypto Credit Card Rewards Taxable?, and ask a qualified tax professional about your situation.
How to apply, in short
You can pre-qualify with a soft check that does not affect your credit score. If you continue, Gemini on behalf of WebBank makes a hard inquiry. You also need a Gemini Exchange account (Gemini runs both applications together if you have none). Answers usually come within 60 seconds. Gemini does not publish a minimum credit score, and declined applications cannot be appealed. See Gemini Credit Card pre-approval and Gemini Credit Card requirements for details.
Personal card vs business card
This review covers the personal Gemini Credit Card. The Gemini business card is a separate product with a flat 1.5% reward. The personal card’s agreement bars “business or commercial purposes,” so do not use it for business spending. See our Gemini business credit card review if that is what you need.
Gemini Credit Card pros and cons
| Pros | Cons |
|---|---|
| No annual fee and no foreign transaction fee | 4% tier capped at $300 a month ($12) |
| 3% dining and 2% groceries with no cap listed | 1% on everything else; rate depends on merchant code |
| Rewards in bitcoin or 50+ coins, usually within minutes | Reward value moves with crypto prices; tax record-keeping |
| Soft-pull pre-qualification | APR 18.74%–34.74%; no intro APR |
| Metal card, no number printed | Welcome bonus paused; support and frozen-account complaints; rewards program can change or end |
FAQ
Is the Gemini Credit Card worth it?
Yes, for a narrow group: U.S. cardholders who pay in full, spend on dining and groceries, and want rewards in crypto. A blended rate near 2% is what our example month earned, and the 4% tier is worth at most $12 a month. It is not worth it if you carry a balance or want a bonus.
Is the Gemini Credit Card legit?
Yes, it is a real credit card. It is issued by WebBank, a Utah state-chartered bank, and serviced by Gemini Constellation, LLC, and its terms are published. “Legit” is a separate question from “good service.” BBB shows a B rating, the company is not accredited, and many users complain about support and frozen accounts (see the cons above).
Is the Gemini Credit Card good?
It is good at what it is built for: no-fee spending that earns crypto, with a decent dining and grocery rate. It is not good as a one-card-for-everything choice, because of the merchant-code surprises, the 1% base rate and the support record.
What are the Gemini Credit Card benefits?
No annual fee, no foreign transaction fee, crypto rewards of up to 4%, a metal card, mobile wallet support, up to five authorized users and Mastercard World Elite benefits. See the benefits list above.
What rewards does the Gemini Credit Card pay?
4% on gas at the pump, EV charging, transit, taxis and rideshare (first $300 a month, then 1%), 3% on dining, 2% on groceries (not Costco, Sam’s Club or Walmart) and 1% on everything else, paid in bitcoin or another supported coin.
What credit limit will I get?
Gemini does not publish limits. In 33 limits reported by cardholders, the median starting limit was $2,000 and the range was $1,000 to $24,000. Self-reported and unverified.
Does the Gemini Credit Card have a sign-up bonus?
Not currently. The $200 offer was paused for cards approved after January 31, 2026, and we found no public replacement.
Will applying hurt my credit?
Pre-qualifying does not affect your score. If you continue to the full application, Gemini on behalf of WebBank makes a hard inquiry, which can lower your score slightly.
Bottom line
The Gemini Credit Card is a solid no-fee crypto rewards card for U.S. spenders who pay in full and eat out and shop at ordinary supermarkets. It is a weak choice for balance carriers, bonus hunters, Costco shoppers, anyone who needs dependable support, and anyone who wants cash-like certainty from their rewards. Compare it with other U.S. crypto cards in Best Crypto Cashback Cards (2026) before you decide.
Sources
Official and primary
- Gemini Credit Card page
- Gemini Credit Card Rates & Fees, September 25, 2026
- Gemini Credit Card Cardholder Agreement, September 25, 2026
- Gemini support: What rewards tiers are available?
- Gemini support: How do I earn credit card crypto rewards?
- Gemini support: How to manage my Gemini Credit Card
- Gemini support: Application process
- Gemini Credit Card Crypto Rewards Program terms, March 4, 2026
- Gemini intro bonus promotional terms, January 27, 2026
- Gemini Credit Card referral program terms, December 19, 2025
- Costco: payment methods accepted
- BBB profile: Gemini Credit Card and complaints
- Trustpilot: Gemini (company page)
What cardholders report (self-reported, small samples, unverified)
- r/Gemini: “The Gemini Credit Card: great idea, terrible execution”
- r/CreditCards: “Thinking about opening the Gemini Credit Card”
- r/CreditCards: “Gemini Credit Card? Why would anyone use this?”
- r/Gemini: support escalation thread
- r/Gemini: Costco and Sam’s Club (May 2025)
Credit limit and merchant data: see our credit limit study and merchant categories guide for the thread-by-thread sources.
Read next
Gemini credit card limits: 33 real reports
What starting limit cardholders actually got, and how increases work.
Which merchants earn 4% on the Gemini card
Merchant-by-merchant results for gas, transit, dining and groceries.
How the main crypto cashback cards compare on rates and fees.
Disclaimer
CryptoCashbackCard is an independent site. We are not affiliated with, sponsored by, or endorsed by Gemini or WebBank. The Gemini Credit Card is issued by WebBank. This page is for general information and is not financial, credit or tax advice. Reward rates, categories, caps, APRs and fees are set by the issuer and can change at any time. Cardholder reports are self-reported, come from small samples and are not verified by us. Always check the current terms in your Gemini account before you apply or spend.
Last updated: October 31, 2026. Author: CryptoCashbackCard.