Source: Business CHA §17 / §31 (Sep 25, 2026)
Key Takeaways
- Eligibility (as of Oct 25, 2026): Sole proprietors and single-member LLCs can apply; all other entity types are on an active waitlist. [Gemini product page]
- Rewards: Flat 1.5% crypto back on all purchases — no category tiers stated on the business product page.
- Fees: $0 annual fee and $0 foreign transaction fee (Business CHA Pricing Supplement, Sep 25, 2026).
- Purchase APR: 18.74%–34.74% variable (Prime 7.00% as of Sep 25, 2026 + margins 11.74%–27.74%).
- Welcome bonus: Historical $500 crypto after $6,000 / 90 days — paused for approvals after Jan 31, 2026 11:59:59 PM ET. [Intro Promo Terms]
- Credit reporting: Account reported to business and/or consumer CRAs in the Business name (+ guarantor if applicable); defaults may appear on your credit report.
- SMLLC gotcha: Personal guaranty — applicant is jointly and severally liable for Account obligations.
- FCBA: Federal Fair Credit Billing Act does not apply to this business-purpose Account.
Most pages ranking for “gemini business credit card review” still cover the personal Gemini Credit Card. This page is the business product only: the Gemini American Business Card (Mastercard World Elite Business), issued by WebBank and serviced by Gemini Constellation, LLC. We curated eligibility, APR/fees, the paused welcome bonus, and credit-reporting contract language from Gemini’s own Cardholder Agreements dated September 25, 2026, and we label Reddit/user reports as anecdotes — not averages.
If you already track the personal card’s category map, our Gemini Credit Card merchant categories guide and Gemini credit limit notes and our personal Gemini Credit Card pre-approval guide (soft vs hard pull) stay useful for the consumer product; numbers below are business-CHA specific unless labeled otherwise.
1 What is the Gemini American Business Card?
It is a WebBank-issued Mastercard World Elite Business card marketed by Gemini, earning flat 1.5% crypto rewards on purchases, with no annual fee and no foreign transaction fee under the Sep 25, 2026 Business Cardholder Agreement. Launched November 11, 2025 for sole proprietors; eligibility later expanded on the product page to include single-member LLCs.
| Metric | Value | Source |
|---|---|---|
| Product name / network | Gemini American Business Card / Mastercard World Elite Business | Product page |
| Issuer / servicer | WebBank / Gemini Constellation, LLC | Business CHA 2026-09-25 |
| Launch | 2025-11-11 | Gemini launch blog |
| Annual fee | $0 | CHA §10a |
| Foreign transaction fee | $0 | CHA Pricing Supplement |
| Rewards | 1.5% crypto flat | Product page |
| Authorized Users | Up to 5 (18+, Gemini account) | CHA §17 |
| Business-purpose only | Personal/family/household use prohibited | CHA intro + §2–3 |
| Sources: gemini.com/credit-card/business; Business CHA PDF Sep 25, 2026; launch blog. | ||
Doctor of Credit covered the launch on November 16, 2025 (bonus, no AF, 1.5%, WebBank) but did not publish a data table and flagged uncertainty on personal credit reporting — one reason this curated review exists.
2 Who can apply — sole prop, SMLLC, waitlist
As of October 25, 2026, Gemini’s business product page states the card is available to sole proprietors and single-member LLCs. All other entity types can join an active waitlist. SMLLC applicants provide a personal guaranty and are jointly and severally liable for Account obligations under the Business CHA.
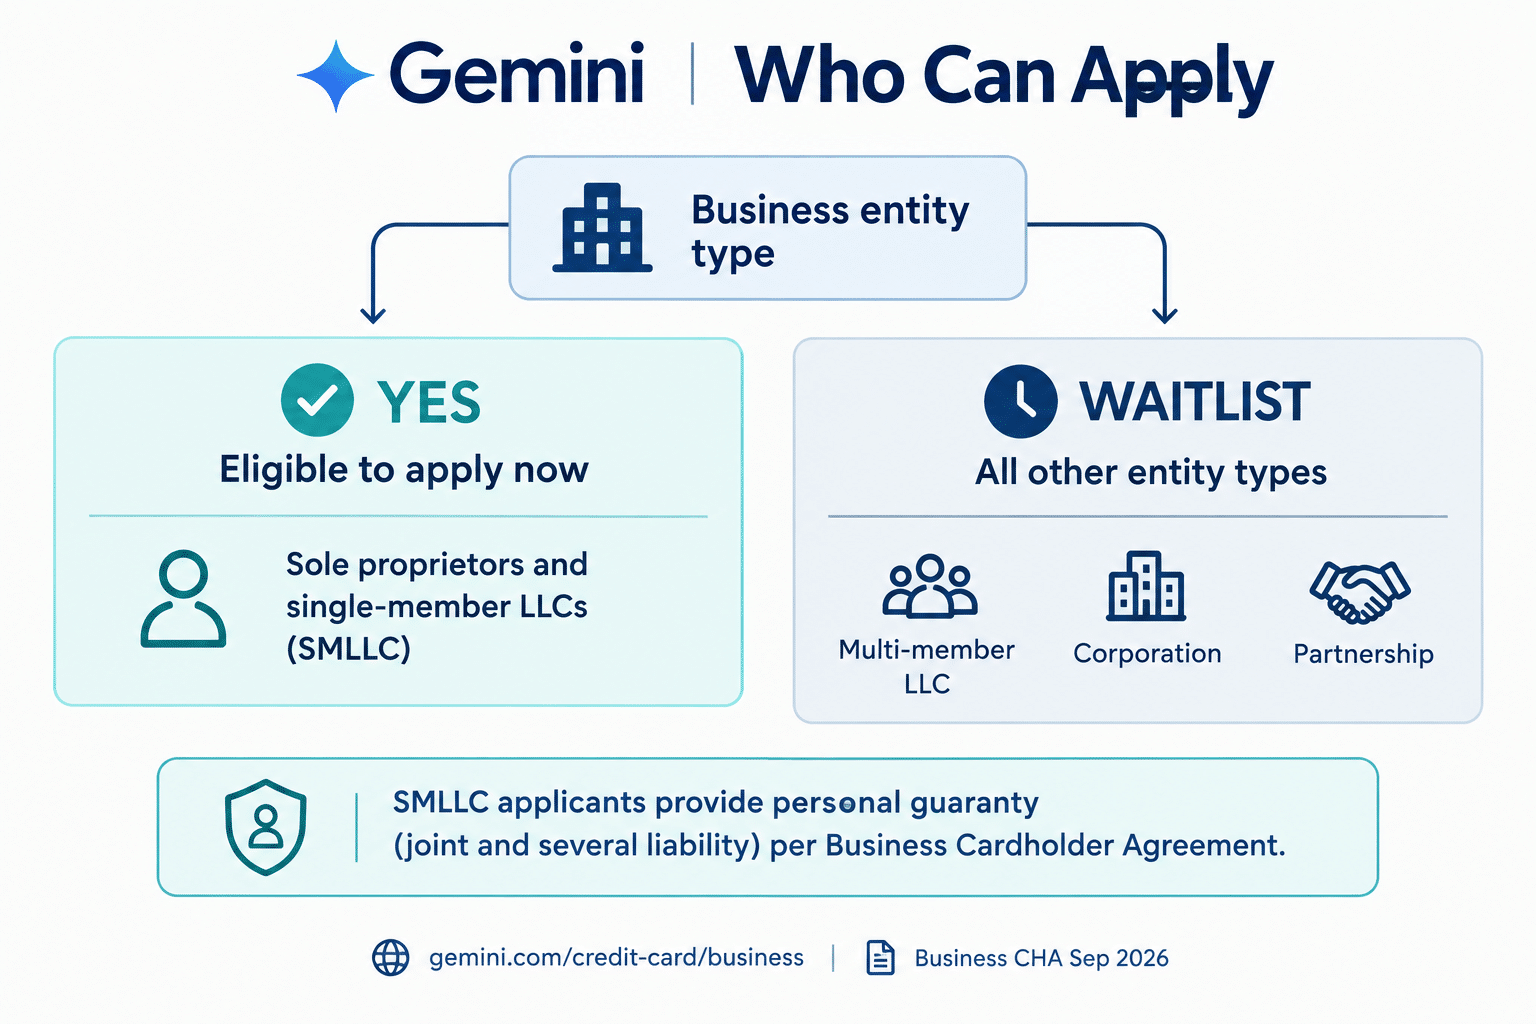
Reddit threads include corporation applicants reporting waitlist status, which aligns with the official waitlist — but Gemini has not published an official answer on switching entity type mid-application without reapplying.
3 Rewards: 1.5% flat vs personal tiers
Business earns a flat 1.5% crypto on all purchases. Personal earns a tiered 4% / 3% / 2% / 1% structure with a $300/month gas–EV–transit cap and grocery exclusions. Both currently show $0 annual fee and $0 foreign transaction fee.
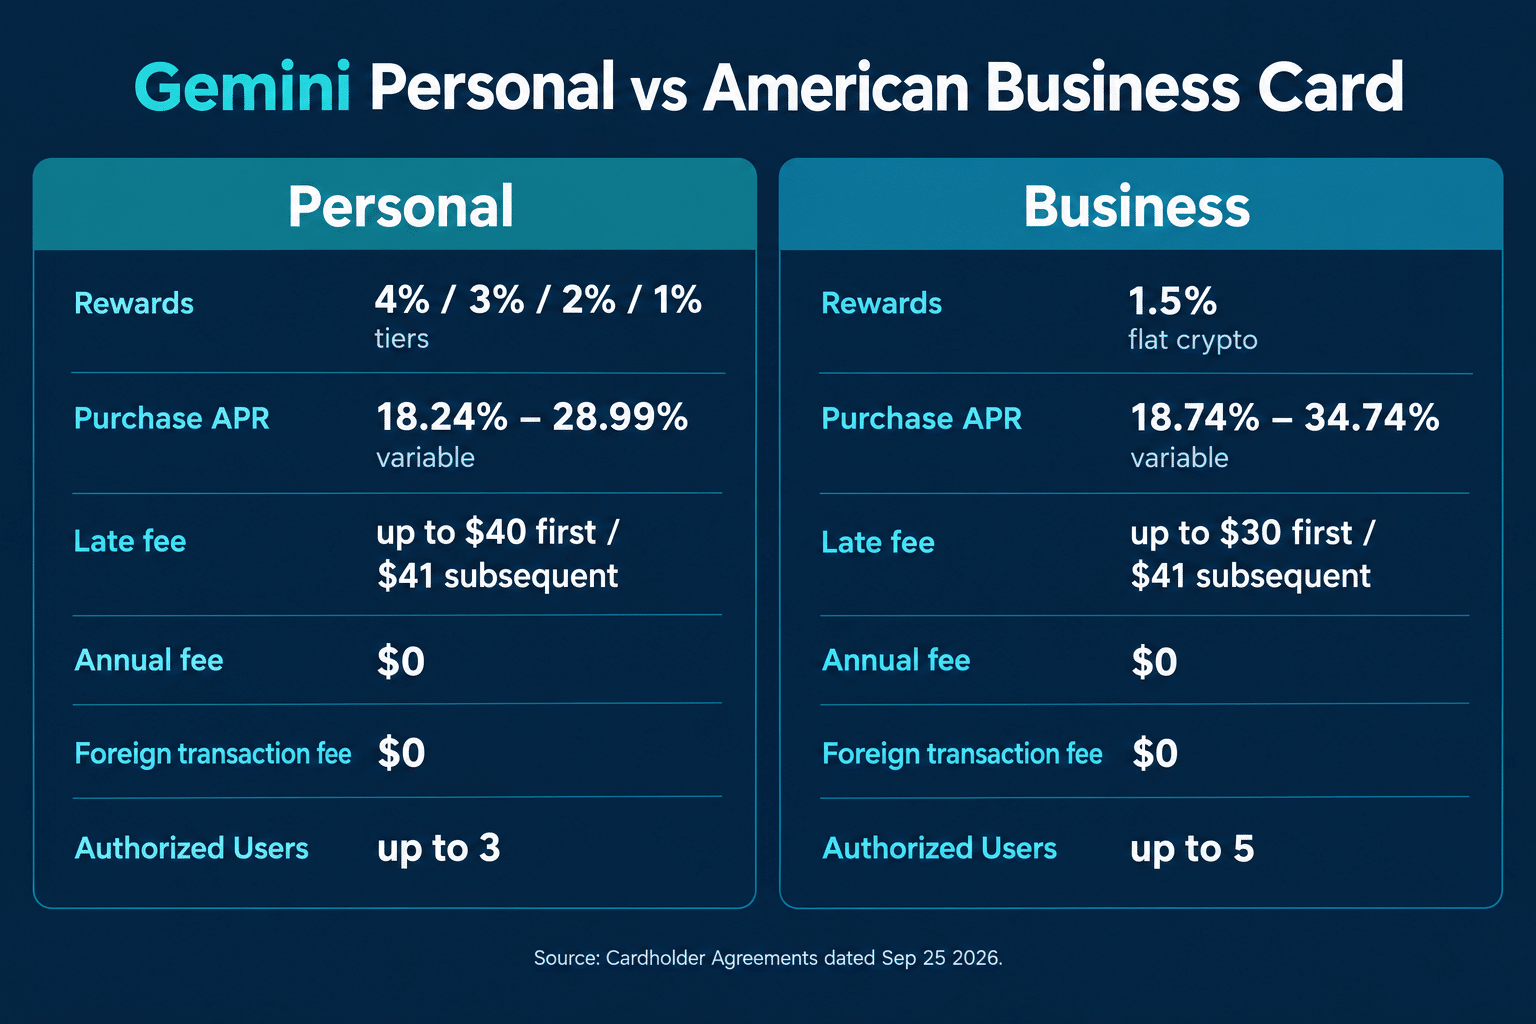
| Feature | Personal Gemini Credit Card | American Business Card |
|---|---|---|
| Rewards | 4% / 3% / 2% / 1% tiers | 1.5% flat crypto |
| Gas / EV / transit | 4% up to $300/mo, then 1% | 1.5% (no stated cap) |
| Dining / grocery / streaming / rideshare | 3% (grocery excludes superstores/wholesale/discount) | 1.5% |
| Online & delivery | 2% | 1.5% |
| All other | 1% | 1.5% |
| Annual fee | $0 | $0 |
| Foreign transaction fee | $0 | $0 |
| Purchase APR (variable) | 18.24%–28.99% | 18.74%–34.74% |
| Late fee (first / subsequent) | Up to $40 / $41 | Up to $30 / $41 |
| Returned payment fee | Up to $40 | Up to $30 |
| Cash advance fee | Either $10 or 5% | Either $10 or 5% |
| Prime (as of 2026-09-25) | 7.00% | 7.00% |
| Margins over Prime | 11.24%–21.99% | 11.74%–27.74% |
| Authorized Users | Up to 3 | Up to 5 |
| Eligibility (high level) | Consumer applicants | Sole prop + SMLLC open; other entities waitlist |
| Sources: Personal CHA & Business CHA Pricing Supplements dated 2026-09-25; personal/business product pages. APR ranges are variable and credit-dependent. | ||
Rule of thumb from the math: if most of your spend sits in personal’s 3–4% buckets under the caps, personal wins on earn rate. If spend is uncapped “other” or you need business-purpose spend with up to five Authorized Users, business’s flat 1.5% is simpler — and often better than personal’s 1% floor. Use the estimator in §11.
4 Rates & fees (Sep 25, 2026 CHA)
Business purchase APR is 18.74%–34.74% variable (Prime 7.00% as of Sep 25, 2026 + margins 11.74%–27.74%). Cash Advance APR is 28.74%–34.74% variable. Penalty APR is 34.74% variable and may apply for 60+ day delinquency or payment returned for insufficient funds. Annual fee $0; foreign transaction fee $0.
| Fee / rate | Amount | Notes |
|---|---|---|
| Annual fee | $0 | CHA §10a |
| Purchase APR | 18.74%–34.74% variable | Prime + 11.74%–27.74% |
| Cash Advance APR | 28.74%–34.74% variable | Prime + 21.74%–27.74% |
| Penalty APR | 34.74% variable | 60+ days late or NSF return |
| Late fee | Up to $30 first; up to $41 later | Pricing Supplement |
| Returned payment | Up to $30 | Pricing Supplement |
| Cash advance fee | $10 or 5% (greater) | Pricing Supplement |
| Foreign transaction | $0 | Pricing Supplement |
| Minimum Interest Charge | $0.50 | Pricing Supplement |
| Grace period | At least 25 days from statement close for Purchases if prior balance paid in full | CHA §9 |
| Source: Business CHA + Pricing Supplement, Sep 25, 2026. Prime rate stated as 7.00% as of that date. | ||
5 Welcome bonus history & Jan 31, 2026 pause
The historical intro offer was $500 in crypto after $6,000 qualifying Purchases within 90 days of approval. Per Gemini’s Credit Card Intro Promo Terms, that offer does not apply to Accounts approved after January 31, 2026 at 11:59:59 PM Eastern Time. Check the product page before applying — we treat the bonus as paused for new approvals after that deadline.
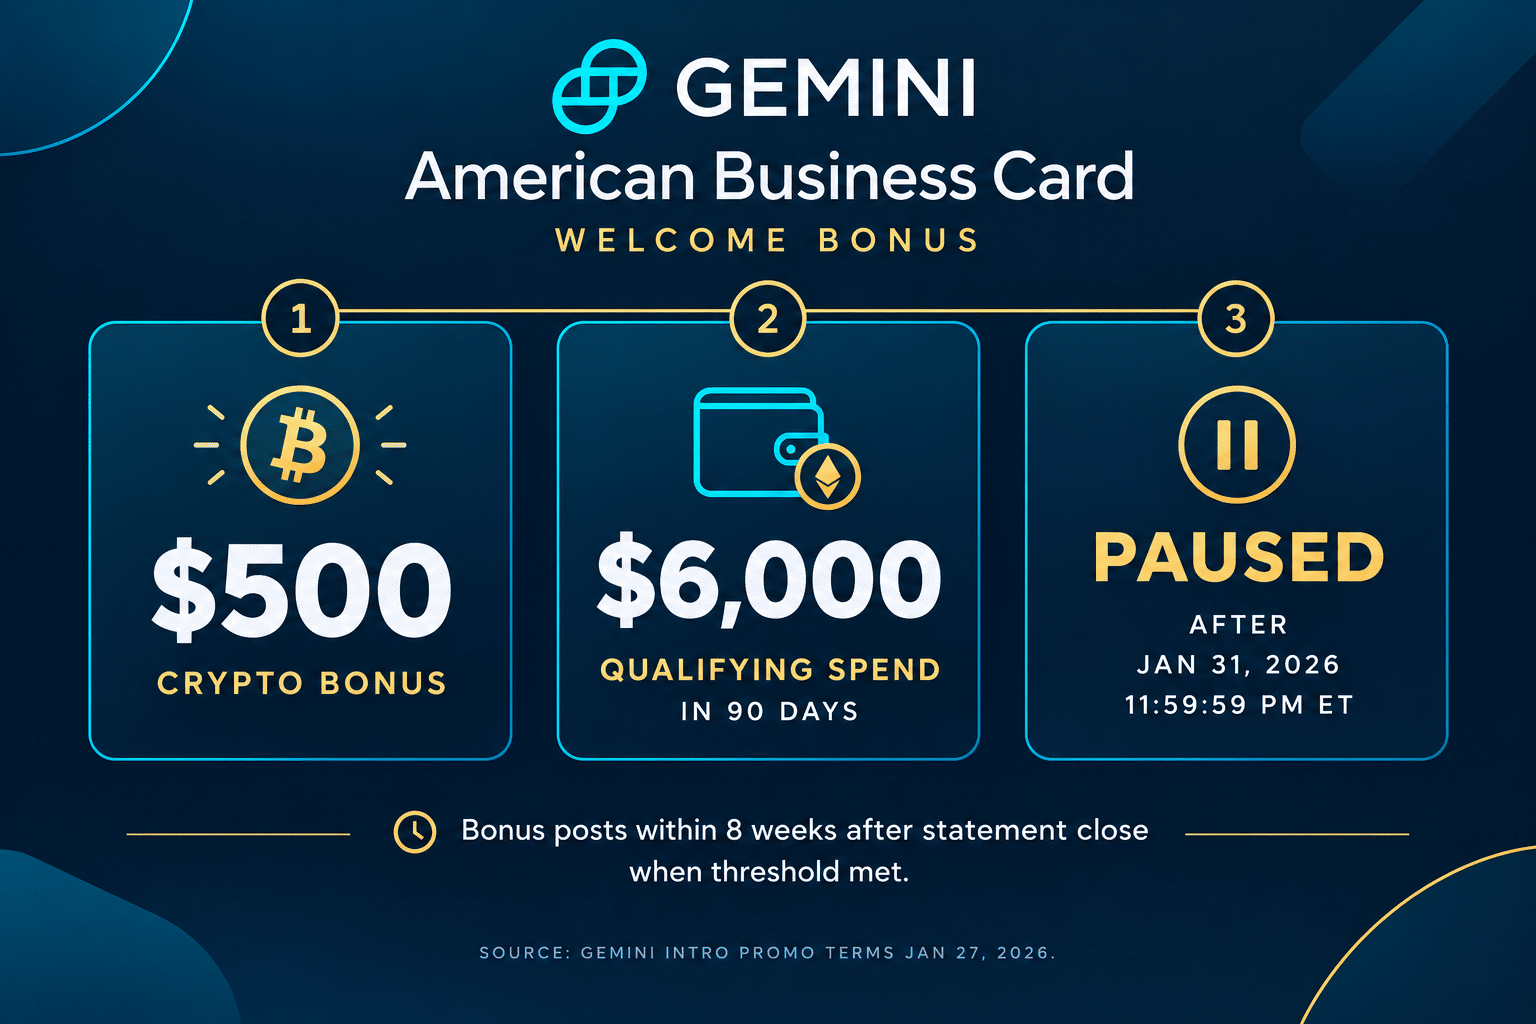
Launch coverage (Gemini blog Nov 11, 2025; Doctor of Credit Nov 16, 2025) described the $500 BTC bonus for sole props. Treat that as historical unless a new promo page appears.
6 Does it report to personal credit?
Yes, under the Business Cardholder Agreement: WebBank/Gemini report the Account to business and/or consumer reporting agencies in the name of the Business and any personal guarantor. Defaults may appear on your credit report. Gemini’s Experian/Equifax support article describes the personal Gemini Credit Card and should not be cited as business-specific reporting practice.
That answers the open question Doctor of Credit flagged at launch more clearly than Reddit anecdotes. It does not mean every tradeline will show on every consumer bureau for every applicant — only that the Agreement authorizes business and/or consumer CRA reporting, including guarantor exposure for SMLLCs.
7 Limits, available credit quirks & anecdotes
Gemini does not publish average credit limits for the American Business Card. The initial Credit Limit is disclosed in the approval email / Pricing Supplement. Public anecdotes exist (including one reported $15,000 business limit) — treat them as single-user reports, not averages. Pending Purchases and Cash Advances can reduce Available Credit even before they post.
| Claim | Type | What we know |
|---|---|---|
| Official average limit | Not published | CHA: limit disclosed at approval |
| Anecdote: ~$15,000 business limit | Single-user report | Reddit / forum anecdotes — not an average |
| Pending auth hold reduces Available Credit | Contract | Business CHA Available Credit language |
| Credit Limit may change | Contract | CHA — issuer may increase/decrease |
| Do not cite anecdotes as “typical starting limits.” For personal-card limit discussion see our Gemini credit limit notes. | ||
8 Holding both personal and business cards
Yes — subject to credit approval. Rewards accrue to separate balances. Gemini’s product materials state you must wait a period of time after opening one card before applying for the other; the exact length is not quantified on the product page we reviewed.
Operationally that means you cannot treat the two products as one pool for category hacking. Personal still owns the high earn tiers; business owns flat 1.5% and business-purpose Authorized User capacity. Internal links for adjacent research: personal card pre-approval (soft vs hard pull), personal Gemini credit card requirements, Gemini XRP rewards notes, are crypto credit card rewards taxable?, and our best crypto cashback cards hub.
9 Reddit-reported gotchas (qualitative)
These are labeled user reports from Reddit/forums — useful for diligence questions, not for statistics. We did not invent frequencies or convert anecdotes into percentages.
- Entity / waitlist friction: Corporation applicants report waitlist status consistent with the official “other entities” waitlist.
- Application timing: Users discuss waiting after opening the personal card before applying for business (matches Gemini’s unquantified wait language).
- Limit expectations: Isolated high-limit reports circulate; they are not averages.
- Support / app experience: Mixed qualitative comments typical of fintech cards — not measured here.
- FCBA reminder: Separate from Reddit — the CHA itself says federal Fair Credit Billing Act does not apply because this is a business-purpose Account; a commercial written inquiry process applies instead.
10 Who it fits / who should skip
| Profile | Fit? | Why |
|---|---|---|
| Sole prop / SMLLC needing business-purpose card + crypto rewards | Strong | Open eligibility; $0 AF; $0 FTF; 1.5% flat |
| Heavy “other” spend that would earn 1% on personal | Strong | 1.5% beats personal’s 1% floor |
| Need up to 5 Authorized Users on one Account | Strong | Business allows 5 vs personal’s 3 |
| Spend concentrated in personal 3–4% categories under caps | Weak as primary | Personal earn rate still higher |
| Multi-member LLC / corp / partnership needing a card now | Not yet | Waitlist only as of Oct 25, 2026 |
| Expecting the $500 intro bonus as a new applicant | No | Paused after Jan 31, 2026 for new approvals |
| Want consumer FCBA dispute rights | Mismatch | CHA: FCBA does not apply |
| Want to avoid personal guaranty exposure (SMLLC) | Mismatch | SMLLC guaranty is joint & several |
11 Personal vs business rewards estimator
Illustrative annual crypto earn assuming stated category rates and the personal $300/mo gas–EV–transit cap. Not a prediction of your APR, limit, or tax treatment. Crypto redemption value still depends on market price at sell/spend.
Worked example (illustrative annual crypto earn using the default mix below — not a prediction of your APR, limit, or tax treatment):
- Gas / EV / transit: $3,600
- Dining + grocery + streaming + rideshare: $6,000
- Online & delivery: $3,000
- All other: $12,000
- Total spend: $24,600
| Card | Illustrative annual crypto earn | Notes |
|---|---|---|
| Personal (tiered) | $474.00 | 4% on first $3,600 gas/EV/transit, then 1%; 3% dining mix; 2% online; 1% other. Grocery MCC exclusions not modeled. |
| Business (1.5% flat) | $369.00 | 1.5% × $24,600 |
On this mix, personal earns more. Heavy “all other” / no-category spend can flip the comparison toward the business card’s flat 1.5%. Crypto redemption value still depends on market price at sell/spend.
12 Frequently asked questions
Who can get the Gemini American Business Card?
Per Gemini’s product page (accessed 2026-10-25), sole proprietors and single-member LLCs can apply. All other entity types can join an active waitlist. [Source]
Does the Gemini business card report to personal credit?
The Business Cardholder Agreement (2026-09-25) states the Account is reported to business and/or consumer reporting agencies in the name of the Business and any personal guarantor. Defaults may appear on your credit report. Gemini’s Experian/Equifax support article describes the personal Gemini Credit Card and should not be treated as business-specific. [CHA]
Is the $500 BTC welcome bonus still available?
No for new approvals after January 31, 2026 11:59:59 PM Eastern Time per Gemini’s Credit Card Intro Promo Terms. The historical offer was $500 crypto for $6,000 qualifying spend in 90 days. [Promo terms]
How does the business card’s rewards compare to the personal Gemini card?
Business: flat 1.5% crypto on all purchases. Personal: tiered 4%/3%/2%/1% with a $300/mo gas–EV–transit cap and grocery exclusions. Both: no annual fee and no foreign transaction fee per current Cardholder Agreements dated Sep 25, 2026.
Can I hold both the personal and business Gemini cards?
Yes, subject to credit approval. Rewards go to separate balances. Gemini requires waiting a period of time after opening one before applying for the second; the exact length is not quantified on the product page.
What are typical starting limits on the Gemini business card?
Gemini does not publish average limits. The Cardholder Agreement says the initial Credit Limit is disclosed in the approval email/Pricing Supplement. Public anecdotes include one reported $15,000 business limit — treat as a single-user report, not an average.
Do personal consumer billing rights (FCBA) apply?
No. The Business Cardholder Agreement states the federal Fair Credit Billing Act does not apply because it is a business-purpose account; a commercial written inquiry process applies instead.
Are crypto credit card rewards taxable?
Tax treatment depends on jurisdiction and how you use the crypto. See our separate guide: Are crypto credit card rewards taxable? This review does not give tax advice.
13 Methodology & sources
This page is a Phase 3 DataGap linkable asset for cryptocashbackcard.com. Facts were curated on October 25, 2026 (America/Chicago) from Gemini’s Business and Personal Cardholder Agreements (dated September 25, 2026), Pricing Supplements, product pages, intro promo terms, the November 11, 2025 launch blog, and Doctor of Credit launch coverage. Reddit/forum comments are labeled as anecdotes and never converted into averages. Charts were generated with KIE.ai (gpt-4o-image) from the fact sheet visual plan — decorative styling in images is not official Gemini branding; cite the tables and CHA PDFs for numbers.
- Gemini American Business Card product page
- Business Cardholder Agreement (2026-09-25)
- Credit Card Intro Promo Terms
- Launch blog (2025-11-11)
- Personal Gemini Credit Card product page (comparison only)
- Fact sheet:
ccc-gemini-business-card-2026-10-25/fact_sheet.md