By the CryptoCashbackCard Editorial Team. Facts checked October 28, 2026; VERIFY refresh same evening (America/Chicago).
Short answer
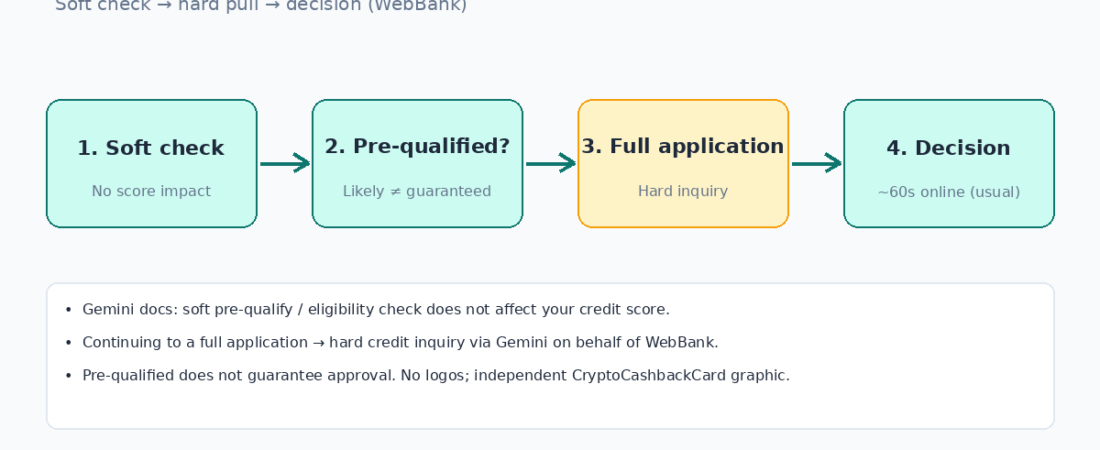
Gemini lets you pre-qualify (what most people search as “pre-approval”) for the Gemini Credit Card with a soft credit check that does not affect your credit score. If you are pre-qualified and continue to a full application, Gemini — on behalf of WebBank — runs a hard inquiry, which can affect your score (Gemini Support: Application Process; Gemini Credit Card).
- Pre-qualified ≠ approved. Gemini says you are “likely” to be approved, but pre-qualification does not guarantee it.
- You also need a Gemini Exchange account (or both the card and Exchange applications run together).
- There is no appeal if you are declined.
- Gemini does not publish a minimum credit score for the card. Any 670 / 690+ numbers you see online are third-party recommendations or forum chatter — not Gemini policy.
This guide maps the soft → hard path, a pre-apply checklist, and what applicants report when they still get denied. It is general information, not approval odds.
Who issues the card
The Gemini Credit Card is issued by WebBank and runs on Mastercard. Gemini’s product overview says residents of all 50 U.S. states may apply (terms and restrictions apply) and that the card is not available outside the U.S. (Gemini Support: Product Overview). WebBank underwrites credit decisions; Gemini markets and services the product.
If you are comparing personal vs. business products, see our Gemini Business Credit Card review. That hub is for product positioning — this article does not claim the Business Card uses the same pre-qualify flow or the same WebBank underwriting rules as the personal Gemini Credit Card.
Soft pull vs. hard pull: how Gemini pre-qualification works
Gemini’s preferred language is pre-qualify or check eligibility. Searchers usually say pre-approval. Same funnel:
| Step | What happens | Credit impact (per Gemini) |
|---|---|---|
| 1. Pre-qualify / check eligibility | Soft look at credit history and other personal information; if eligible, you may see estimated terms before deciding to continue | No impact on your credit score |
| 2. Continue to full application | You provide additional information; Gemini on behalf of WebBank pulls your credit report for a final decision | Hard inquiry — can impact your score and appear on your credit report |
| 3. Decision | Often within about 60 seconds online; sometimes Gemini asks for more info by email or phone | Hard inquiry already happened if you submitted the full app |
Gemini’s consumer marketing uses the same soft-then-hard sequence in card-page footnotes: “Checking if you’re eligible will not impact your credit score… If you’re eligible and choose to continue with your application, we will conduct a hard credit inquiry… Eligibility does not guarantee approval.” We re-verified that footnote wording on gemini.com/credit-card/btc on October 28, 2026 (America/Chicago). The main gemini.com/credit-card page CTA label is Get started (links to Gemini’s hosted apply flow at creditcard.exchange.gemini.com); page meta also says “See if you’re eligible.” Soft/hard rules above still come first from Support.
For a plain-English primer on soft vs. hard inquiries, Gemini points readers to Experian’s educational material (Application Process FAQ).
What “pre-qualified” actually means
From Gemini Support, word for word in substance:
- You have taken the first steps toward approval.
- You are likely to be approved.
- Even so, pre-qualification does not guarantee you will be approved.
Treat a “yes” on the soft check as a green light to consider the hard pull — not as a promise of a card.
Pre-apply checklist
Before you leave the soft-check screen (and especially before you submit a full application):
- Confirm you can apply where you live. Product overview: 50 U.S. states; not available outside the U.S. Terms and restrictions still apply.
- Have (or be ready to open) a Gemini Exchange account. Card approval requires Exchange approval. If you do not already have one, Gemini runs both processes when you apply for the card.
- Unfreeze Experian and Clarity if frozen. Gemini’s freeze FAQ says you must unfreeze both Experian and Clarity (Clarity’s freeze portal is separate) or the application will not continue. After unfreezing, sign back into the Gemini app to continue (Application Process — frozen file).
- Use Gemini’s own eligibility / pre-qualify flow (site or app), not random emailed “you’re invited” links you do not trust. On gemini.com/credit-card the visible CTA is currently Get started (apply host: creditcard.exchange.gemini.com). Soft check first; decide later whether the hard pull is worth it.
- Know that identity must clear. If Gemini cannot verify your identity from its sources, Support says it cannot approve the application under regulatory requirements — separate from credit underwriting.
- Optional: Plaid income verification for a higher limit offer. Gemini Support’s Plaid FAQ tells applicants to select “Up to $5,000 credit limit, Additional income verification needed” to share income via Plaid Check, or to continue with the original offer via the alternate control Support describes as “$ credit limit, No additional income verification needed” (dollar amount shown in-app). Sharing income is optional; opting out “will not negatively impact your eligibility for a Gemini Credit Card,” but the higher limit is not guaranteed (Application Process — Plaid).
Is there a minimum credit score?
Gemini does not publish an official minimum FICO or Vantage score on the Application Process FAQ, Product Overview, or main credit-card marketing page (checked October 28, 2026).
What you will see elsewhere:
- Bankrate lists a “recommended” credit score band of roughly 670–850 (Good to Excellent) in its Gemini Credit Card review — that is Bankrate’s recommendation, not a Gemini cutoff (Bankrate review).
- Google AI Overviews and YouTube often repeat 670 / 680 / 690+ as if they were official. Those numbers are not sourced from Gemini Support.
Approval depends on WebBank’s full underwriting (credit history, income, obligations, identity, Exchange status, and more) — not a public score floor. We do not invent approval odds.
If you are declined
- Reasoning: Gemini says you receive the reason for a decline by email.
- No appeal: Support states there is no appeal process.
- Trying again: The same FAQ describes going through pre-qualification again (soft, no score impact). If you pass soft check and submit a full application again, that triggers another hard pull. Pre-qualify again still does not guarantee approval.
- Identity failures: Support’s “failure to identify” note says they could not verify identity with their sources and therefore cannot approve. Some applicants on public forums report being told they cannot re-apply after an identity denial; that conflicts with the “pre-qualify again” path above. We cannot resolve the conflict from public docs — if this happens to you, rely on your decline email and Gemini support, not forum advice.
What applicants report (self-reported, not odds)
Public r/Gemini threads are skewed toward problems. Treat these as anecdotes:
- People advise using the pre-qualify tool first and avoiding a cold hard application.
- Some report very fast soft-check denials (seconds) after an in-app “will not affect credit” prompt.
- Some denials are framed as identity / name / SSN / DOB verification, not score.
- At least one applicant attributed a denial to high credit utilization despite a high score.
- One commenter claimed you can re-try pre-approval about every 30 days without hurting credit. Gemini has not published that cadence — unverified.
Sources for these reports (checked October 28, 2026): r/Gemini declined / pre-approval thread; credit score before applying; score / pre-qualify reliability.
After approval: limits and next reads
If you are approved, your starting limit and any later increase button are a separate topic. We tracked self-reported starting limits (median $2,000 in that sample) in Gemini Credit Card Credit Limit: 33 Real Limits, Median $2K.
Plaid’s optional income path during application is one of the few official levers Gemini describes for a higher starting-limit offer — still not a guarantee.
For product positioning and rewards categories (not identical underwriting), start at the Gemini Business Credit Card review hub in this cluster. Still deciding whether Gemini is the right card? See how the best crypto cashback cards compare on rates and fees.
FAQ
Does Gemini Credit Card pre-approval hurt my credit score?
The soft pre-qualify / eligibility check does not, per Gemini. Submitting the full application after you are pre-qualified triggers a hard inquiry that can affect your score.
Is “pre-approval” the same as “pre-qualify”?
For this card, yes in practice. Gemini’s docs say pre-qualify / check eligibility; searchers usually say pre-approval.
Does pre-qualification guarantee I’ll get the card?
No. Gemini says you are likely to be approved, but pre-qualification does not guarantee approval.
Who pulls my credit — Gemini or WebBank?
Gemini Support says Gemini, on behalf of WebBank, makes the hard inquiry for the final decision. WebBank is the issuer.
Do I need a Gemini Exchange account?
Yes. Card approval requires Exchange approval. If you do not have an Exchange account yet, Gemini runs both processes when you apply for the card. For the full list of what you need before you check eligibility, see our Gemini credit card requirements checklist.
What credit score do I need?
Gemini does not publish a minimum. Third-party reviews (for example Bankrate’s 670–850 “recommended” band) are not official cutoffs.
What if my credit is frozen?
Gemini’s FAQ says to unfreeze Experian and Clarity, then continue in the Gemini app.
Can I appeal a denial?
No. Gemini Support says there is no appeal process. The FAQ describes pre-qualifying again (soft); a later full application is another hard pull.
Can I skip Plaid?
Yes. Sharing income via Plaid is optional. Gemini says opting out does not negatively impact eligibility for the card, but your limit follows the original offer criteria.
How fast is the decision?
Gemini says online applicants usually get an answer within about 60 seconds; sometimes they request more information by email or phone.
Sources
Official (checked October 28, 2026 unless noted):
- Gemini Support, Gemini Credit Card Application Process: https://support.gemini.com/hc/en-us/articles/4405098390043-Gemini-Credit-Card-Application-Process
- Gemini Support, Product Overview: https://support.gemini.com/hc/en-us/articles/4405148512923-Product-Overview
- Gemini Credit Card marketing page (CTA): https://www.gemini.com/credit-card
- Gemini Credit Card marketing footnotes (soft/hard eligibility language, re-checked on BTC variant): https://www.gemini.com/credit-card/btc
Editorial (score band is theirs, not Gemini’s):
- Bankrate, The Gemini Credit Card® review: https://www.bankrate.com/credit-cards/reviews/gemini-crypto-card/
Applicant reports (self-reported, unverified), checked October 28, 2026:
- r/Gemini — Declined / rejected for Gemini Credit Card ‘Pre-approval’
- r/Gemini — What credit score before applying?
- r/Gemini — What credit score is needed for the Gemini card?
Disclaimer
CryptoCashbackCard is an independent site. We are not affiliated with, sponsored by, or endorsed by Gemini, Gemini Trust Company, LLC, Gemini Constellation, LLC, or WebBank. “Gemini” and related marks are trademarks of their owners and are used here only to identify the product. This page contains no affiliate or referral links. It is general information, not financial, credit, or legal advice. Community reports are self-reported, unverified, and may be outdated. Card terms, underwriting, and Support FAQs can change — always check the current terms on Gemini’s site, in the Gemini app, and in your cardholder agreement. We do not guarantee pre-qualification, approval, any credit limit, APR, or rewards outcome. The Gemini Credit Card is issued by WebBank.