Data checked Oct 2026 from each issuer’s official pages and card terms. No sponsored placements.
Short answer
For most people with no crypto balance, the Gemini Credit Card pays the most with no membership: 4% on gas, EV charging and transit (first $300 a month), 3% dining, 2% groceries, 1% everything else, $0 annual fee. If you already keep large balances on Coinbase or Kraken, their cards can match or beat that, but only at high balance tiers.
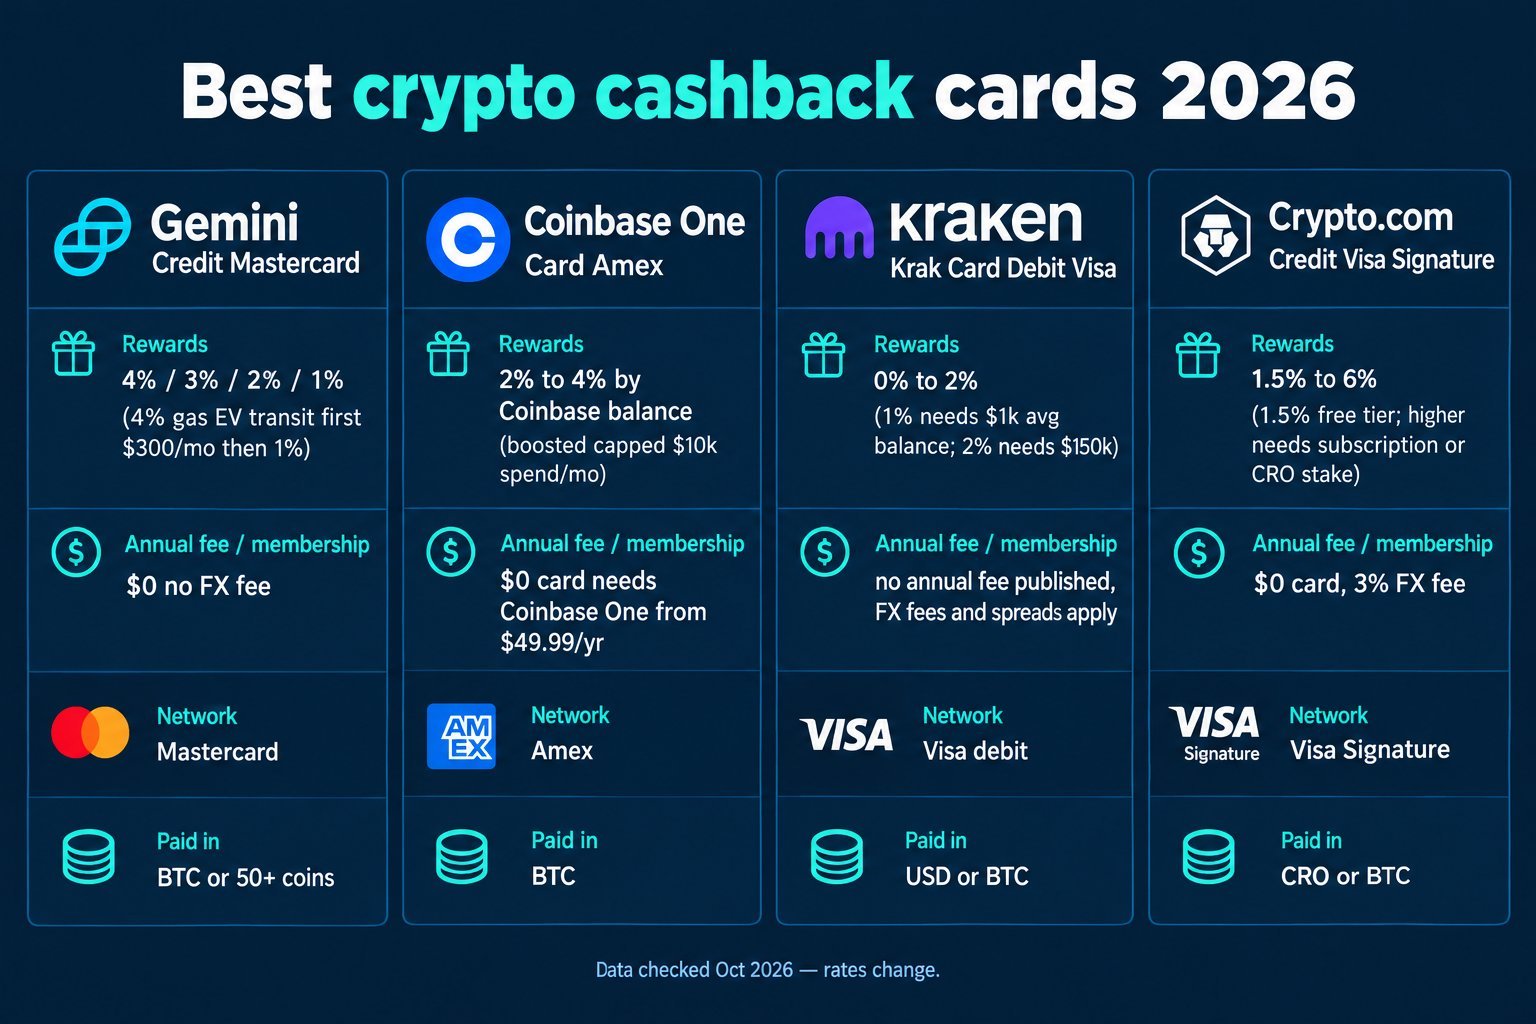
The four main US crypto cashback cards, side by side
| Card | Rewards | Fees | Credit check | Paid in |
|---|---|---|---|---|
| Gemini Credit, Mastercard |
4% / 3% / 2% / 1% 4% on gas, EV, transit: first $300/mo, then 1% |
$0 No FX fee |
Hard pull Prequal has no score impact |
BTC or 50+ coins, switchable |
| Coinbase One Card Credit, Amex |
2% to 4% Rate set by your Coinbase balance; boosted rates capped at $10k spend/mo |
$0 card Needs Coinbase One, from $49.99/yr; no FX fee |
Hard pull Prequal has no score impact |
BTC |
| Krak Card Debit, Visa |
0% to 2% 1% needs $1k avg balance; 2% needs $150k |
No annual fee published FX fees and spreads apply |
Not a credit card ID and SSN check only |
USD or BTC |
| Crypto.com Credit, Visa Signature |
1.5% to 6% 1.5% free tier; higher needs a subscription or CRO stake |
$0 card 3% FX fee; tiers from $4.99/mo |
Credit check on apply Prequal has no score impact |
CRO or BTC BTC capped monthly |
Rates change often. Krak isn’t available in NY, ME, MA or IN, and its balances aren’t FDIC or SIPC insured.
Which card fits you
- No crypto balance, spend on gas or commuting: Gemini. You get its top rate without holding anything. See which stores actually pay 4%, and which drop to 1%.
- Big Coinbase balance: Coinbase One Card. Its 4% tier needs a large balance on Coinbase plus the paid membership, so count the membership in your math.
- You want debit, not credit: Krak. There’s no credit line and no credit application, but rewards start at $1,000 average balance. Why Krak’s top 2% rate now needs $150,000.
- You already hold or stake CRO: Crypto.com. The free tier pays 1.5%; the big rates need a paid tier or a CRO stake, and travel abroad costs a 3% FX fee.
Gemini Credit Card
Gemini pays 4% on gas at the pump, EV charging, transit, taxis and rideshare for the first $300 you spend in those categories each month, then 1%. Dining earns 3%, groceries 2%, everything else 1%. Rewards land in your Gemini account within minutes, in bitcoin or any of 50+ coins. There’s no annual fee and no foreign transaction fee. Issued by WebBank.
Whether a purchase earns 4% depends on how the store is coded, not on what you bought. Approval odds? See the median starting limit from 33 cardholder reports.
Coinbase One Card
Bitcoin back is 2%, 2.5%, 3% or 4%, depending on your assets on Coinbase when you buy. The boosted tiers stop after $10,000 of purchases a month, then 2%. Travel booked through Coinbase One Card Travel earns 5%. The card itself has no annual fee, but you must keep a paid Coinbase One membership (from $49.99 a year); if it lapses, the card can be closed.
Krak Card
Krak’s Visa debit card spends from your Krak balance. Since Oct 15, 2026, cashback depends on your 30-day average balance across Krak and Kraken: 0% under $1,000, 1% from $1,000, 1.5% from $10,000, 1.75% from $75,000, 2% from $150,000. New cardholders get the top rate for their first 30 days. You pick USD or BTC payouts. Issued by Lead Bank.
Crypto.com Visa Signature Credit Card
The free Basic tier pays 1.5% in CRO, or 1.5% in BTC on the first $250 a month and then 1%. Paid tiers raise it: 3.5% (from $4.99 a month), up to 6% at the top tier, which requires a large CRO stake. No annual card fee, but a 3% foreign transaction fee. Issued by Comenity Capital Bank.
Also worth a look: the Fold Bitcoin Credit Card pays 1.5% in bitcoin with no cap and no annual fee, rising toward 5% only if you park a large balance with Fold.
Before you sell those rewards: crypto you earn from a card can create a tax bill later. See when crypto card rewards become taxable and how Coinbase taxes work.
Read next
This page is general information, not financial or tax advice. We don’t earn commissions from any card listed here. Check each issuer’s current terms before you apply.